Last updated November 18, 2026
Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Construction Emergency Preparedness Guide for Anaheim Homes
The contractor knocking on your door at 6 a.m. the day after a burst pipe or a fire is usually not from Anaheim. He’s from two counties over, following storm and disaster leads. What he hands you to sign in that adrenaline-soaked first hour can cost you your insurance rights and, occasionally, the value of your house. This guide is built for the homeowner on the other side of that door: the one who wants to know what to photograph, what to check, what to refuse, and how to hire correctly when the ground is still wet. We’ll cover the pre-event documentation that saves claims, the Anaheim-specific structural risks that actually matter, and the exact sequence that separates emergency stabilization from permanent repair.
Quick Answer
Construction emergency preparedness in Anaheim means documenting your home’s current condition before anything happens, knowing the specific risks of your seismic zone and the Santa Ana fire interface, and refusing to sign any agreement – especially assignment-of-benefits paperwork – in the first 48 hours after damage. The single most protective step is having dated photos, a written condition record, and your insurance policy details in a folder you can grab and hand to a licensed contractor and your adjuster. In our experience, homeowners who do that baseline work settle claims faster and pay far less out of pocket than homeowners who start from scratch when the water is already rising.
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
Table of Contents
- How to Document Your Home Before an Emergency
- Pre-Event Structural Checks That Matter in Anaheim
- The First 48 Hours: What to Do and What Not to Sign
- How to Verify a Contractor’s License in Real Time
- Stabilization vs. Permanent Repair: Two Contracts, Not One
- Planning the Permanent Repair Correctly
- Working With Your Insurance Adjuster
How to Document Your Home Before an Emergency
The homeowner who has a file ready when damage hits is in a completely different position from the one who doesn’t. Insurance claims are decided on evidence, and evidence requires a baseline – proof of what your home looked like before the event, not after. In Anaheim, where a single burst pipe can cost $8,000 to $22,000 in water damage and reconstruction depending on how far it spreads, that baseline is worth real money.
Here’s what to build, and it takes one afternoon:
- Walk every room and shoot dated photos. Open cabinet doors, photograph under sinks, look up under the roof from the attic access, and capture every wall. Turn on the date stamp or keep a written log with dates.
- Photograph the systems. Water heater, electrical panel, HVAC equipment, the underside of bathrooms (from the ceiling below, if accessible), and the foundation at the perimeter. These are the items adjusters question most.
- Write a one-page condition record. Note any existing cracks, stains, or prior repairs. Documenting a small pre-existing stain protects you from being blamed for a pre-existing condition when a pipe bursts.
- Store it in two places. Cloud backup plus a physical folder with your insurance policy number, agent contact, and this document record.
- Photograph receipts and serials. For appliances and fixtures – your Kohler and Moen fixtures, your cabinetry – a photo of the model plate makes replacement valuation far easier.
Do this now, in a normal week. The day after a fire is too late to prove what the kitchen looked like.
Pre-Event Structural Checks That Matter in Anaheim
Anaheim sits in a genuine seismic zone, so people assume earthquakes are the main event. They’re one of three. The two others are the Santa Ana wind corridor and the fire interface zone that pushes right up against the canyons and hillsides. The checks below address all three.
Seismic checks
- Water heater strapping. Verify your water heater is secured with proper seismic straps. An unstrapped heater is the most common earthquake-triggered water loss cause in Anaheim homes, and a ruptured tank can dump 40 to 50 gallons before anyone notices.
- Foundation and cripple-wall inspection. Look for diagonal cracking, settlement, or unbolted sill plates at the base of walls. A pre-event assessment here means you know whether your house has a known vulnerability before the ground tells you.
- Chimney and masonry anchorage. Older Anaheim homes often have unreinforced masonry. A focused inspection of anchorage is worth the trip.
Fire interface checks
- Roof-to-wall connections and vents. Ember intrusion at vents and soffits is a leading cause of home loss in Santa Ana wind events. Check that vents are fitted with fine mesh, not just wide screening.
- Siding condition. Cracks, gaps, and failed caulk in siding create ember traps. We install James Hardie fiber cement siding in part because it handles heat exposure better than vinyl or wood, but the installation detail matters more than the material.
- Defensible space. Clear vegetation and debris within five feet of the foundation and roof perimeter.
These are inspection points, not a do-it-yourself project list. A licensed general contractor can assess them, and if something needs reinforcing, that’s a written-scope conversation.
The First 48 Hours: What to Do and What Not to Sign
Here’s the part that decides whether your claim goes smoothly or becomes a fight. In the first 48 hours after structural damage, your goal is to stop ongoing damage and protect yourself. It is not to rebuild.
- Make it safe and stop the damage. Shut off gas and water at the main if needed. Call your insurance company to open a claim immediately – the claim number matters more than the contractor choice right now.
- Photograph everything before anyone touches it. Damage evidence is your leverage. Once debris is hauled to the curb, that record is gone.
- Do not sign an assignment-of-benefits (AOB) agreement. This is the single most important rule in this guide. An AOB transfers your right to negotiate and collect the insurance payout over to a contractor. He then bills your insurer, and you become a bystander in your own claim. In Florida, AOB abuse drove the state to change its law outright. Don’t sign one without having a public adjuster or your insurer review it first. Ask a contractor to explain, in writing, exactly what the document transfers.
- Get a scope in writing, not a verbal ballpark. Any reputable contractor will put what he intends to do, and the price, on paper before work starts. A verbal estimate that changes at the door is the most common complaint we hear from burned homeowners in Anaheim.
- Verify the license before anyone starts. More on this in the next section.
Storm chasers target households in exactly this window. The urgency they manufacture – “sign tonight, the price goes up tomorrow” – is a signal to slow down, not speed up.
How to Verify a Contractor’s License in Real Time
California licenses contractors through the Contractors State License Board. The check takes under two minutes, and you should do it on your phone while the contractor stands in front of you. There is no reason to take a license number at its word.
- Go to the CSLB website (cslb.ca.gov) and use the “Check a License” tool. This is the only authoritative source.
- Enter the license number from the contractor’s card. Confirm the name on the record matches the business you’re talking to – not a different entity entirely.
- Check the status. It should show “Active” or “Licensed.” An expired, suspended, or “unlicensed” status is a stop.
- Look at the classification. A general building contractor classification (B) covers the type of structural and remodel work a home emergency oftentimes requires. A license limited to a specialty trade can’t legally take on general repair scope.
- Confirm the bond and insurance. California requires contractors to carry a surety bond, and workers’ compensation must be on record if the business has employees. The CSLB record shows this.
If a contractor is unlicensed, he cannot legally contract for work over $500, and your insurance may not cover his work. In Anaheim, we’ve seen claims stall for weeks because the repair was done by an unlicensed operator. A licensed, insured, bonded contractor will not hesitate to be verified. A storm chaser will.
Stabilization vs. Permanent Repair: Two Contracts, Not One
This is the distinction that protects your home and your wallet, and it almost never gets explained. Emergency stabilization and permanent repair are two different jobs, two different scopes, and – if a contractor is honest – two different contracts.
Stabilization means making the house safe and stopping ongoing damage. Boarding up, tarping, shoring, tarping a roof, extracting standing water, and turning off utilities. It’s temporary by design. It should be fast, minimal, and priced as a discrete scope.
Permanent repair means restoring the building correctly – replacing what was damaged, matching existing materials, and passing inspection. This is where the real rebuild happens and where plans, permits, and a written line-item price belong.
Why split them? Because a single “everything” contract signed in the first 48 hours commits you to a scope you haven’t designed yet, at a price nobody has verified. It’s also how AOB problems get baked in. We recommend:
- A short written stabilization scope with a fixed price. Get it done, get it documented, and get the receipt for your insurer.
- A separate written permanent-repair contract once your adjuster has reviewed the damage and you’ve had time to design the repair.
In our experience, the homeowners who keep those two jobs separate settle claims faster and avoid the “the price changed after demo” conversation entirely. The Kingswell standard is simple and we apply it here: say the price before the work, show up in the window we gave, leave the place cleaner than we found it. That standard applies to a tarpaulin as much as it does to a kitchen. You can see how we apply it on our Penhallow Remodeling Anaheim home page.
Planning the Permanent Repair Correctly
Once the home is stabilized and the claim is open, the permanent-repair phase looks a lot like a planned remodel – because it is one. This is where a licensed General Contractor in Anaheim earns the fee. A few things to know about this phase:
- Permits come first. Structural repair, electrical, plumbing, and any envelope work require permits and inspections in Anaheim. A contractor who says the permit “isn’t needed” is telling you the work won’t be inspected and may not be insurable.
- Written line-item pricing, not an estimate range. Every itemized cost – demolition, framing, drywall, finishes, trades – belongs in the contract. If a scope changes after demo, it changes in a written change order, not at the door.
- Materials decision happens here, not at the door. If a bathroom is being rebuilt, this is the moment to choose fixtures thoughtfully. A rebuilt Bathroom Remodeling in Anaheim project lets you upgrade to Kohler or Moen fixtures without the premium-pressure of a crisis. Our team can walk through material options.
- Insurance scope vs. your scope. The insurer covers damage to what was there. If you use the repair as a chance to upgrade the kitchen, that portion is typically out of pocket and belongs in a separate line – our Kitchen Remodeling in Anaheim page explains how we handle that split.
- Ask what happens if the work fails. A written guarantee matters. Our 365-Day Done Right Promise means if the work fails within the guarantee period, we come back and fix it at no charge – in writing, on every project. The check for structural repair is worth what’s underwriting it.
We handle the permanent-repair phase of fire, water, and seismic damage as a planning exercise, not a rush job. That’s the whole point of the two-contract approach: the repair gets designed, priced, and permitted like it deserves.
Working With Your Insurance Adjuster
Your adjuster is not your adversary, but he is overworked, and the quality of the documentation you hand him determines the outcome. A few practices that make the process smoother:
- Submit the baseline documentation from Section 1 immediately. Before and after photos resolve the “pre-existing condition” argument before it starts.
- Keep stabilization and repair receipts separate. Insurers reimburse them differently in many policies.
- Ask for the scope in writing from the adjuster before signing anything. You can compare his line items to your contractor’s written scope and resolve gaps early.
- Note the difference between actual cash value and replacement cost. Many policies pay replacement cost only after you complete the repair and submit receipts. Budget for the gap.
- Ask about code upgrades. Anaheim building codes have changed over the decades, and some policies include a limited amount for code-mandated upgrades discovered during repair. Ask the adjuster directly.
If the damage involves a fire that compromised structural framing, get a licensed structural evaluation before you sign anything with a repair contractor. The general contractor on that job should be able to bring in structural engineering as needed. That’s a service we can coordinate.
Common Mistakes to Avoid
- Signing an AOB in the first 24 hours. It strips your right to negotiate your own claim. Sign nothing you don’t fully understand until your insurer or a public adjuster reviews it.
- Hiring the first door-knocker. Storm chasers follow damage, not zip codes. Ask where the truck is from and verify the CSLB license before letting anyone touch the house.
- Skipping the baseline photo file. Without proof of your home’s prior condition, you argue with your insurer from memory. Build the file now.
- Treating stabilization as permanent repair. A tarp is not a new roof. Get the emergency work quoted and contracted separately from the repair.
- Accepting a verbal estimate. In our experience, the second number that arrives after demo is almost always higher. A written price before work starts is the whole game.
- Letting a contractor pull permits “later.” No permit means no inspection, and unpermitted structural or electrical work can void your insurance and complicate a future sale.
- Forgetting the pre-existing damage record. That crack you’ve had for three years becomes “damage from this event” on the adjuster’s form unless you photographed it first.
See the difference
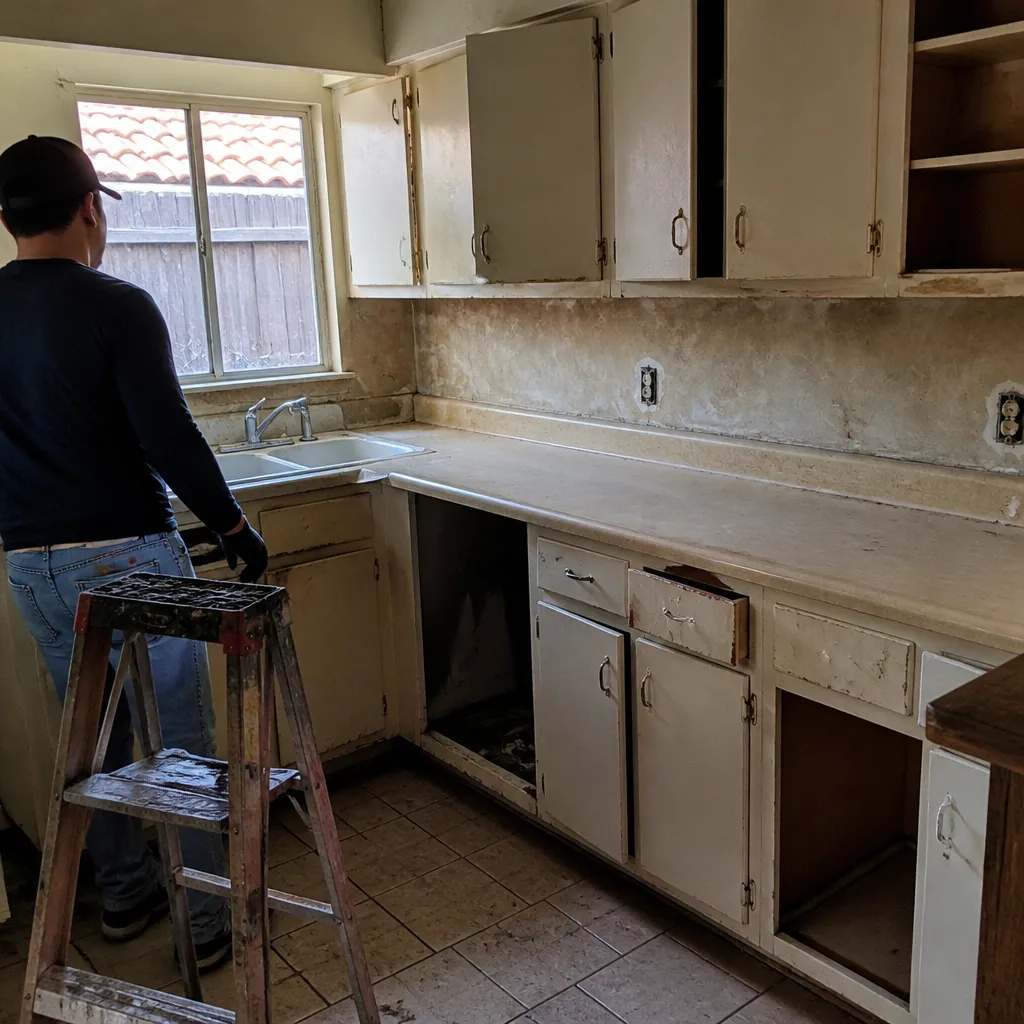 Before
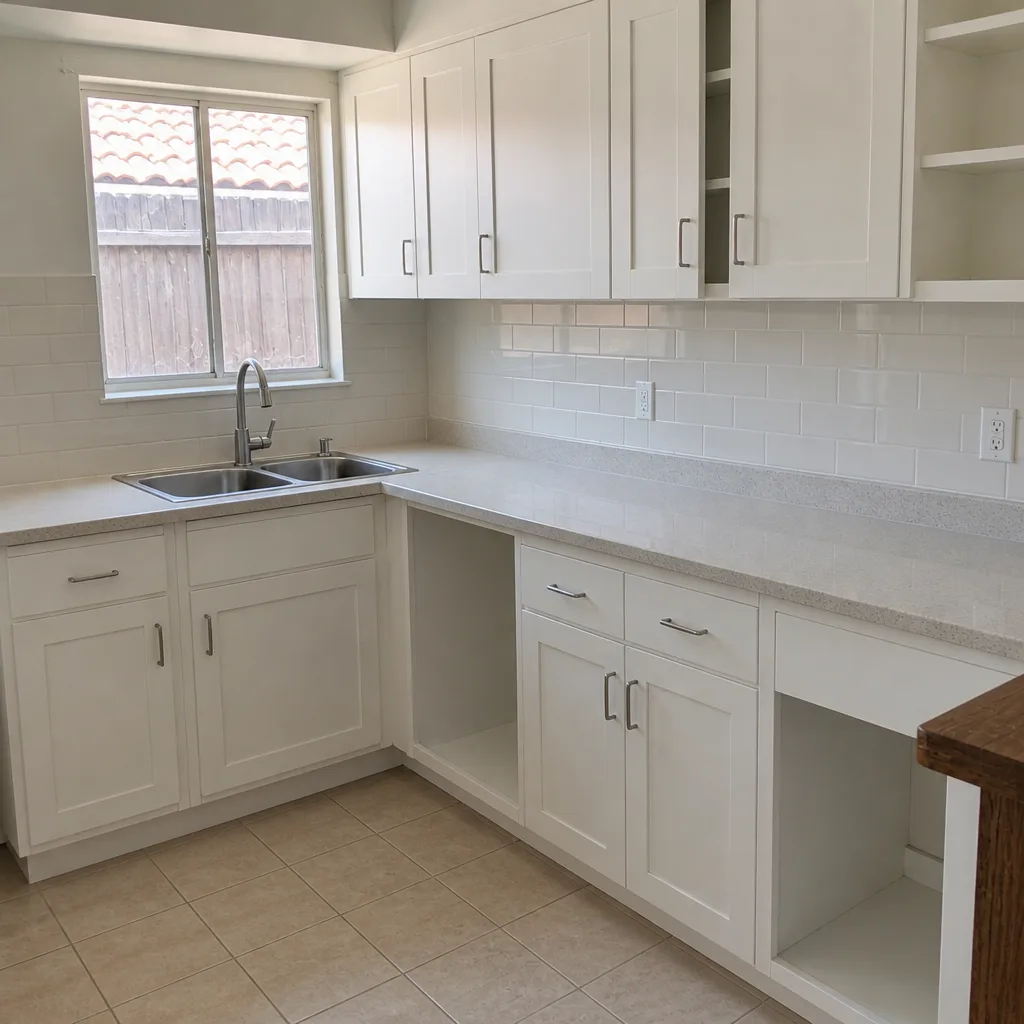 After
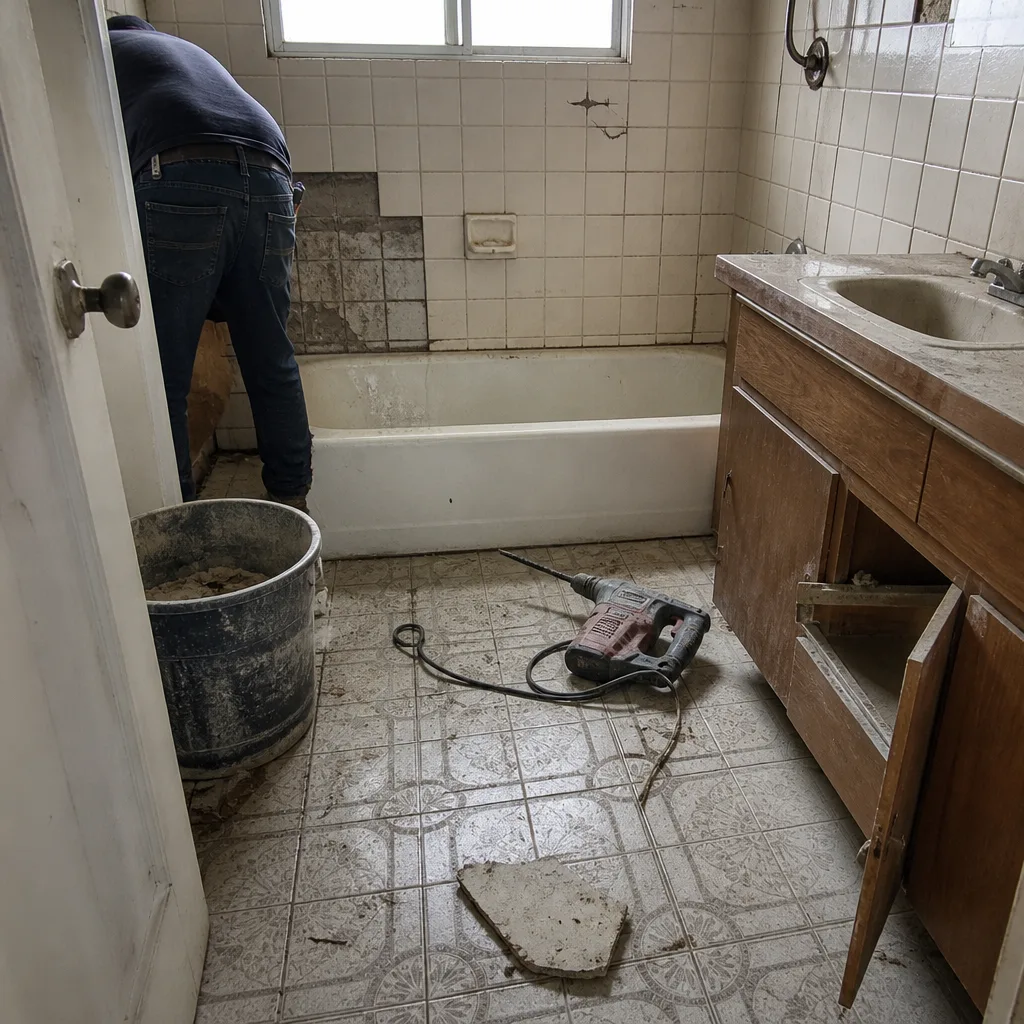 Before
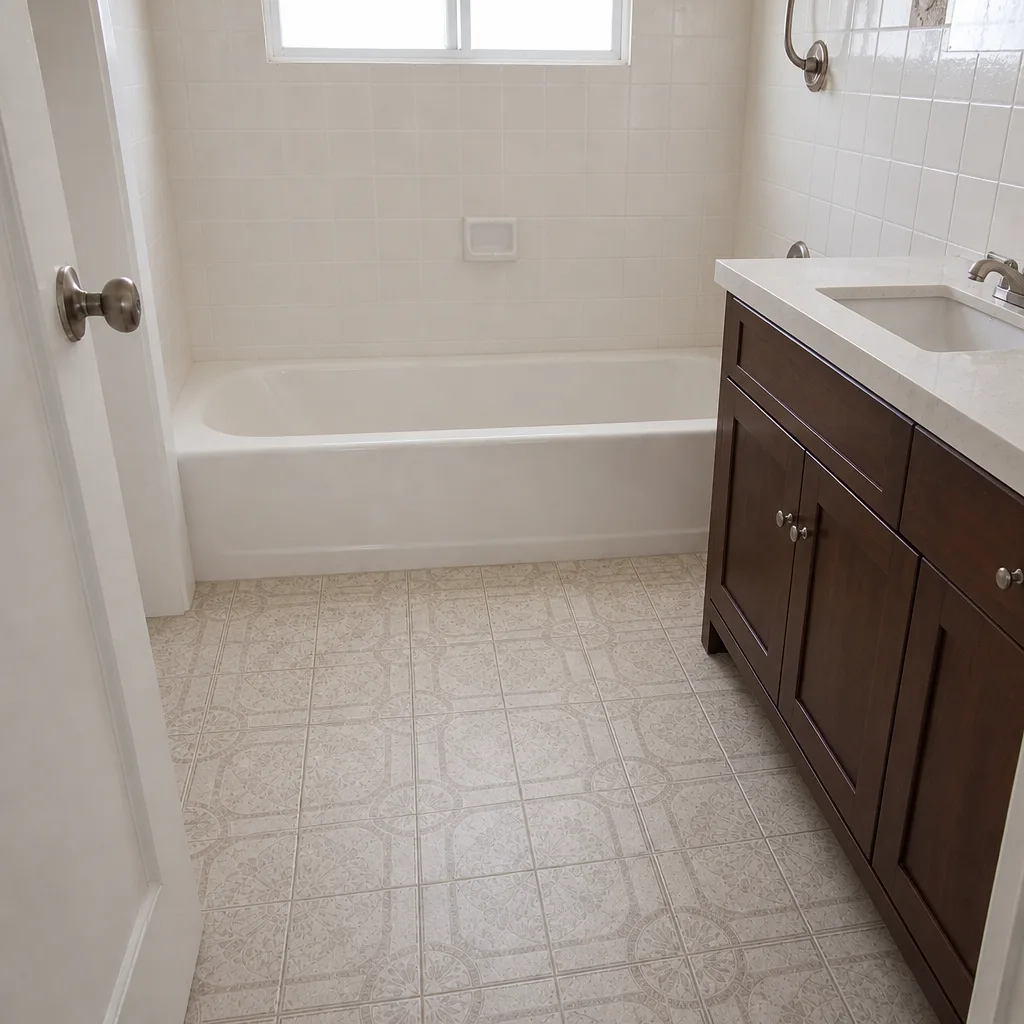 After
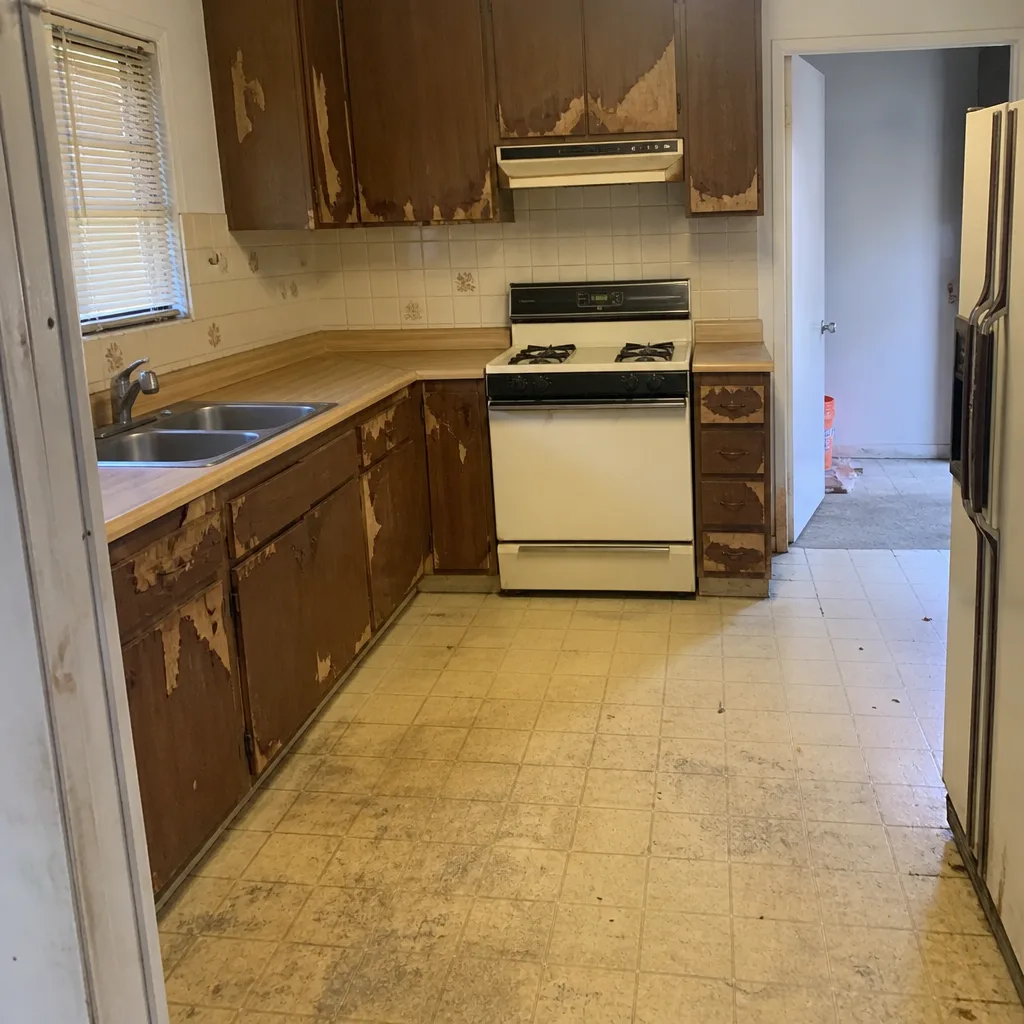 Before
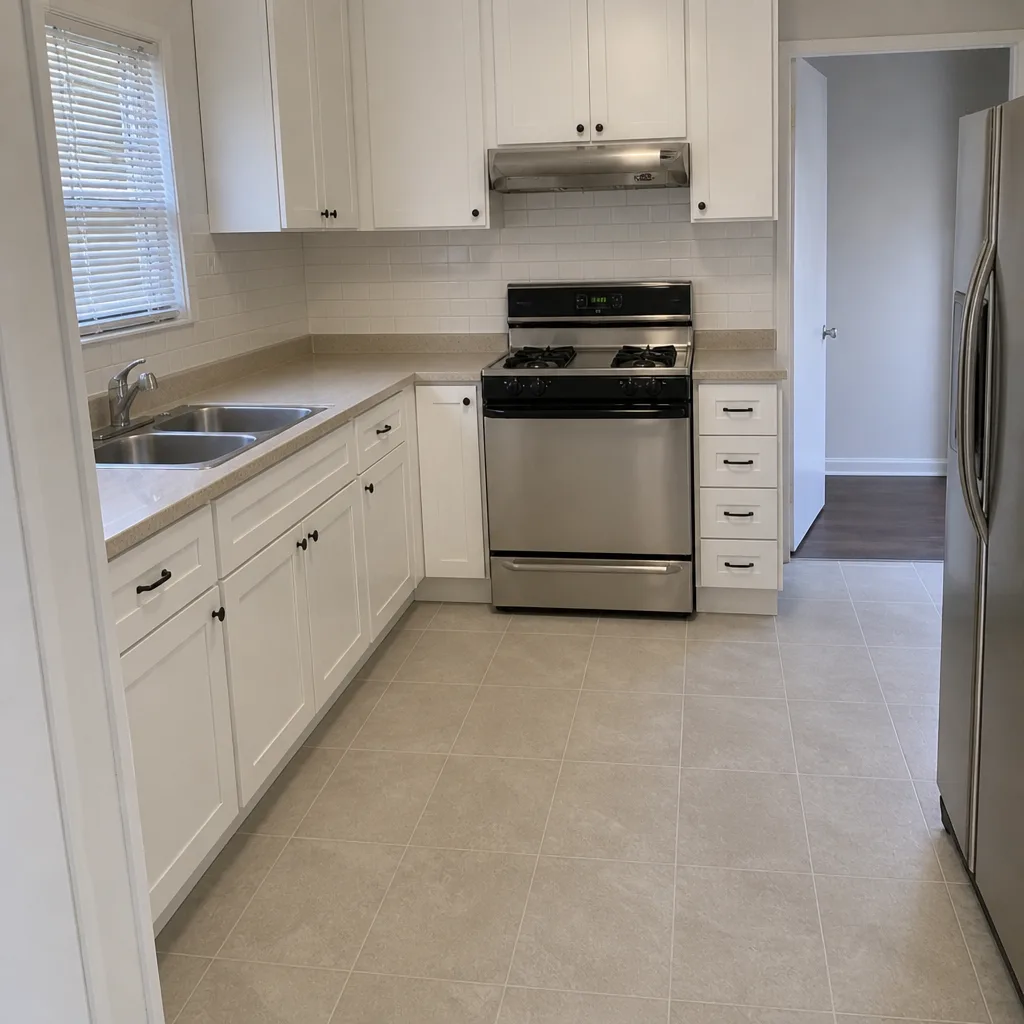 After
When to Call a Professional
Call a licensed contractor the moment any of these are true: the structural framing of the house is involved, the roof is compromised and water is entering, gas or electrical lines are damaged, the damage is more than cosmetic, or your insurer’s scope and the repair contractor’s scope don’t match. On any repair involving framing, load-bearing elements, or a compromised roof, don’t attempt the work yourself – an unanchored wall or a compromised structural roof is a serious safety risk, and the work is a job for a trained professional with the right equipment and insurance. We also recommend having a licensed professional inspect after any event involving fire, since heat damage may extend beyond what’s visible. Penhallow Remodeling Anaheim offers free estimates in Anaheim – call (844) 320-2908 to schedule. We’re a licensed general contractor with background-checked, uniformed technicians, and the same technician standard applies on every job.
Frequently Asked Questions
Shut off the water main, cut power to any wet area at the panel, and open the insurance claim immediately – before choosing a contractor. Photograph everything before debris is moved. Stabilize and dry the structure with a licensed water-damage and repair contractor, and keep the stabilization contract separate from the permanent repair contract. Call (844) 320-2908 if you want a licensed second opinion on the scope.
Water damage reconstruction commonly runs $3,500 to $9,000 for a single-room loss and $8,000 to $22,000 or more when a major system fails and affects multiple rooms, depending on how far the water traveled, whether drywall needs replacement, and whether flooring and cabinetry have to come out. Structural drying itself runs $1,200 to $4,500 depending on equipment and duration. Call (844) 320-2908 for a free, written estimate on the repair scope – our prices are on paper before work starts.
Standard homeowners policies typically exclude earthquake damage, so coverage usually requires a separate earthquake policy or endorsement. Check your policy documents and confirm the deductible before you need it. If a claim is denied, a licensed contractor can still help you scope the repair and price it in writing.
A written price is a binding dollar number the contractor will honor, while a verbal estimate is a ballpark that can change. In our experience, the estimate that changes at the door is the most common complaint we hear. On every project we give a written line-item price before work starts, so the number on day one is the number on the invoice.
You can use the same licensed contractor, but we recommend two separate written contracts – one fixed-price scope for stabilization and one for the repair. That keeps you from committing to a repair scope you haven’t designed or priced yet. It also keeps your claim documentation clean for the adjuster.
Enter the contractor’s license number in the CSLB “Check a License” tool at cslb.ca.gov on your phone before you sign anything or allow work to start. Confirm the status is active, the classification matches the work (a general building B classification for structural repair), and that bond and workers’ compensation are on record. A licensed, insured contractor will not object; a storm chaser will pressure you to skip the check.
Dated photos of every room and system, a written one-page condition record, your insurance policy number and agent contact, appliance and fixture model photos, and a folder of any prior repair receipts. Handing a contractor and an adjuster that file shortens the claim and protects you from the “pre-existing condition” conversation.
The Bottom Line
Anaheim’s emergency risks are real, but preparation beats reaction every time. Document your home today, photograph the systems, and store the file where you can grab it. Know the two checks that matter after an event – the insurance claim and the CSLB license – and refuse to sign an AOB or an ambiguous repair contract in the first 48 hours. Keep stabilization and permanent repair as two separate, written scopes. A licensed, insured contractor, a written price, and a written guarantee are what separate a repaired house from an unresolved claim. That’s what we stand on at Penhallow Remodeling Anaheim.
Schedule Your Free Estimate
If you’re facing damage now or building peace of mind before the next one, call (844) 320-2908 for a free estimate. A live person answers the phone 24/7 – not a voicemail maze. You’ll get a written price before any work starts, background-checked, uniformed technicians on every job, a written guarantee on every repair, and the 365-Day Done Right Promise in writing. If a repair fails inside the guarantee period, we come back and fix it at no charge, with no service call or re-inspection fee. Give us a call.
Written by the team at Penhallow Remodeling Anaheim.